Term Life Insurance · Home Loan Planning
Term Insurance for Home Loan: Level vs Decreasing Term Cover
A practical comparison for salaried home loan borrowers: how decreasing term cover follows a reducing schedule at a lower premium, why level term cover keeps the payout constant for living costs and childcare, what bank-bundled home loan cover typically pays, and a fully reproducible worked example with labelled interest rate and repayment assumptions.
You have just signed a twenty-year home loan, and somewhere between the sanction letter and the first EMI, the bank has placed an insurance proposal in front of you. Before accepting it, understand that term insurance for home loan protection comes in two structurally different forms. The cheaper variant is not automatically the one that protects your family most completely.
This guide compares the decreasing (reducing) term plan, whose cover shrinks on a preset schedule, with the level term plan, whose payout remains constant for the entire policy term. It explains what bank-bundled cover typically pays, and it closes with a worked example you can reproduce using your own loan figures.
Key takeaways
- A decreasing term plan starts with a sum assured equal to the loan and reduces it on a fixed schedule, which is why its premium generally sits below a comparable level term plan (Bajaj Life Insurance).
- A level term plan holds the payout constant for the full term, so the nominee can repay the loan and still retain funds for household costs, childcare and education.
- Home loan cover bundled by a lender is commonly arranged on a reducing-balance basis, with the claim routed to the lender; policies differ, so read the payout and assignment clauses (HDFC Life).
- No general Indian law compels a borrower to hold life cover, but a lender may write insurance conditions into the loan agreement; ask whether an independently purchased policy is acceptable.
- In the worked example below, a Rs 75 lakh loan at 9% per annum leaves roughly Rs 53 lakh outstanding in year ten, a gap that exposes the difference between scheduled and level payouts.
What is term insurance for home loan protection?
Term insurance for home loan protection is a pure life cover whose sum assured, meaning the amount the insurer pays on the policyholder's death, is sized around the outstanding housing loan. The claim proceeds can clear the debt so the family retains the home. No Indian statute compels a borrower to hold such cover, although lenders actively promote it.
A term plan is the simplest form of life insurance. Premiums purchase protection alone, with no savings component and no maturity payout if you survive the term. Because the product carries no investment element, pure term plans generally cost less than life insurance products that bundle savings with cover.
Borrowers researching term life policy insurance for a housing loan usually encounter three distinct products: a lender-bundled home loan insurance policy, a standalone decreasing term plan, or a conventional level term plan. Buyers comparing insurance term life options online should separate these categories before weighing premiums, because the narrowest protection frequently carries the smallest price. A term insurance for home loan calculator on most insurer websites converts your loan size, tenure and age into an indicative premium. If you prefer a guided comparison, QURA's advisors can help you compare term life insurance plans side by side.
How does decreasing term cover track your outstanding loan?
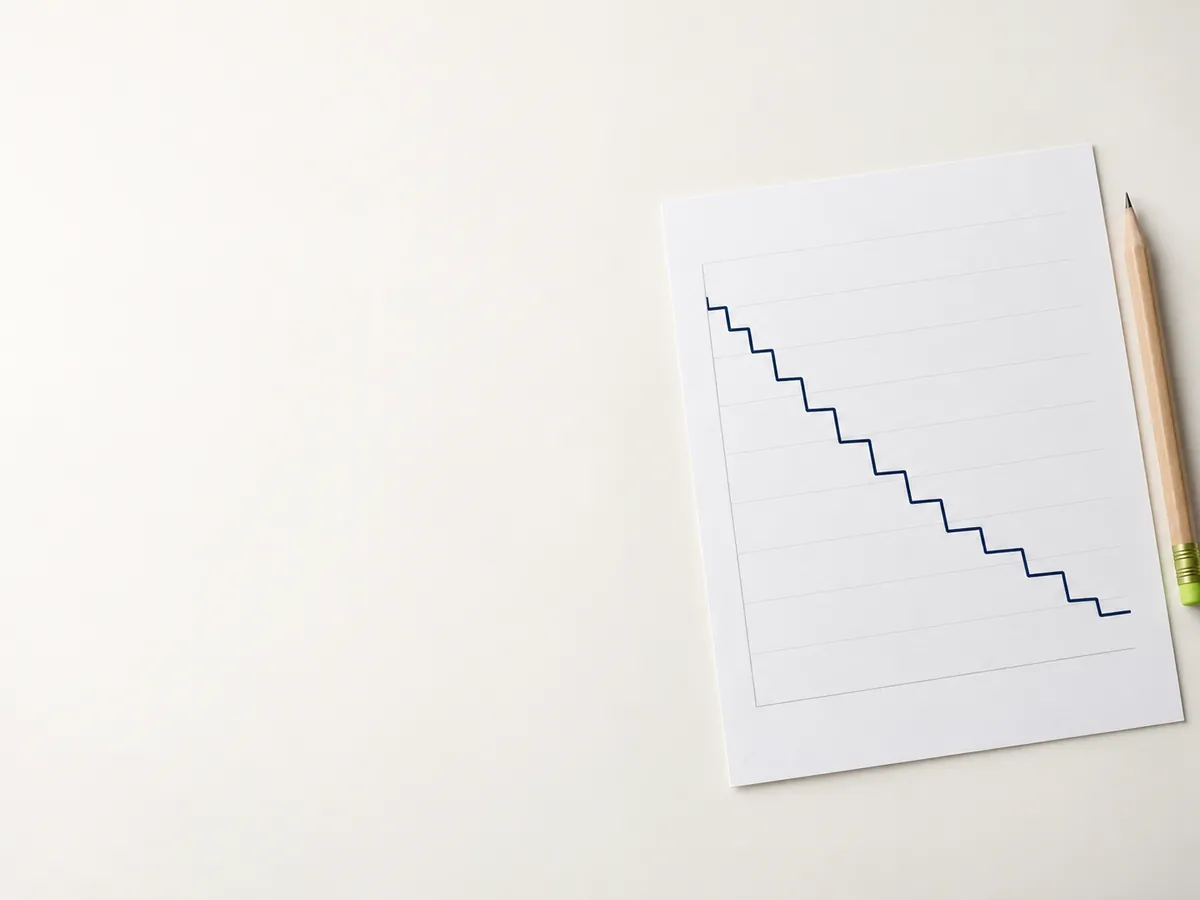
A decreasing term plan opens with a sum assured equal to the sanctioned loan and reduces that figure along a preset schedule, usually once a year. The schedule approximates the amortising balance, yet it can diverge from your actual debt after interest rate resets or part-prepayments. Compare the plan's reduction schedule against your own amortisation table before purchasing.
The insurer's exposure falls as each equated monthly instalment (EMI) chips away at the principal, so premiums on decreasing plans sit below those on level plans of identical starting size.
"Since the coverage reduces as outstanding debt declines, premiums are generally lower than those of a level term insurance plan." (Bajaj Life Insurance)
Share on LinkedIn · Share on X
HDFC Life describes a similar structure in its reducing home loan cover, where protection steps down as EMIs are paid (HDFC Life). Its hybrid variant holds the cover flat through the first year, recognising that early instalments flow mostly toward interest. The trade-off deserves attention. A claim late in the tenure pays far less than the original sum assured, even when the family's other financial needs have not contracted at the same pace.
Level term vs decreasing term insurance: which fits a home loan?
In the level term vs decreasing term insurance decision, the decisive difference is what a claim pays in the later years. A decreasing plan pays a scheduled amount approximating the remaining loan balance. A level plan pays the full sum assured whenever death occurs, so the proceeds can settle the loan and ongoing family expenses together.
A level term plan holds the payout constant from the first policy year to the last. HDFC Life and Bajaj Life explainers describe the same structural consequence: because the benefit never shrinks, a single plan can discharge the mortgage and simultaneously fund living expenses, childcare and school fees. That flexibility matters most for a salaried borrower whose household depends on one income.
At a glance
- Payout path: decreasing cover steps down each year; level cover stays flat for the full term.
- Claim recipient: lender-bundled cover usually pays the lender; a standalone term plan pays your nominee.
- Premium direction: decreasing plans generally price below level plans of equal starting cover (Bajaj Life Insurance).
- Residual benefit: decreasing cover clears the debt alone; level cover can leave a surplus for family costs.
- Best fit: decreasing suits single-debt protection; level suits households with broader, recurring expenses.
What does bank-bundled home loan insurance in India actually cover?
Home loan insurance in India, meaning the cover typically bundled with a housing loan, is a mortgage protection policy that pays only the outstanding balance when the borrower dies. The claim is usually routed to the lender, and the family's wider needs remain unaddressed. A standalone life policy pays the nominee directly and permits broader use of the proceeds.
HDFC Life states the limitation plainly: home loan insurance addresses the outstanding balance of a housing loan, while life insurance supplies a lump sum the family may deploy toward the mortgage, living expenses or other goals (HDFC Life). Policies differ in their assignment and payout clauses, so examine those clauses before relying on bundled cover alone.
Borrowers frequently ask: is term insurance mandatory for home loan approval? No general Indian law compels it. A lender may nonetheless write insurance conditions into the loan agreement, so confirm whether an independently purchased policy satisfies the requirement before accepting the bundled option.
Worked example: what does each plan pay in year ten?
The figures below are illustrative, chosen so you can reproduce them with any amortisation calculator. They are not a quotation, and they ignore part-prepayment and rate resets for simplicity.
- Loan: Rs 75 lakh, twenty-year tenure, 9% per annum with monthly rests.
- EMI: approximately Rs 67,480, computed with the standard amortisation formula.
- Year-ten balance: approximately Rs 53 lakh outstanding after 120 EMIs.
Under a decreasing term plan purchased for Rs 75 lakh at sanction, the scheduled cover in year ten sits close to Rs 53 lakh. A claim at that point discharges the loan and leaves little else. The structure performs precisely the single task it was designed for, nothing more.
Under a level term plan of Rs 1 crore, the same event triggers a Rs 1 crore payout to the nominee. After clearing the Rs 53 lakh balance, roughly Rs 47 lakh remains available for household expenditure, childcare and education. On an illustrative household spend of Rs 60,000 per month, that surplus funds more than six years of expenses.
On cost, Aditya Birla Sun Life Insurance illustrates roughly Rs 575 per month for Rs 1 crore of term cover (Aditya Birla Sun Life Insurance). The figure is indicative rather than a quotation. Your actual premium depends on age, health, smoking status, policy term and underwriting, and decreasing plans generally price below level plans of equal starting cover.
What this means for you
A salaried borrower servicing a fresh home loan should treat the bank's insurance proposal as one option among several, not as a default. Work through the following sequence before committing to any structure.
- Request the full amortisation schedule from your lender and note the balance at years five, ten and fifteen.
- Compare any decreasing plan's reduction schedule against those balances to confirm the cover never falls below the debt.
- Size a level plan at the loan amount plus several years of household expenditure, since the payout must serve two purposes.
- Examine assignment clauses, because a policy assigned to the lender pays the lender first regardless of family needs.
- Buy early, since premiums rise with age and health complications can restrict eligibility later.
If you would rather walk through these numbers with a person than a spreadsheet, book a free call with a QURA expert. The conversation covers your loan schedule, your household's monthly needs and the plans that fit both, with no spam and no sales pressure.
Frequently asked questions
Is term insurance mandatory for a home loan in India?
No general Indian law requires a borrower to hold life cover when taking a home loan. A lender may include insurance conditions in the loan agreement, so ask whether an independently purchased term plan satisfies the condition before accepting bundled cover.
Home loan insurance vs term insurance: which protects my family better?
Home loan insurance pays only the outstanding balance, usually to the lender, so the debt disappears but nothing more. A standalone term plan pays your nominee the full sum assured, which can clear the loan and fund living costs together.
Can I buy term insurance for an existing home loan?
Yes. You can purchase a term plan at any point during the tenure, sized to the current outstanding balance plus family expenses. Premiums depend on your age and health at application, so delaying typically raises the cost.
What happens to my term plan if I prepay the home loan?
A level term plan remains fully in force regardless of prepayment, and the payout stays constant until the term ends. A decreasing plan follows its own schedule, so prepayment can leave the cover higher than the reduced debt, which is harmless.
How much term cover do I need alongside a home loan?
A common approach adds the outstanding loan to several years of household expenditure, childcare and education costs. An advisor can help you calibrate the figure against your income, dependants and existing cover before you commit.
Sources
- Term Life Insurance
- Home Loan Planning
- term insurance for home loan
- level term vs decreasing term insurance
- home loan insurance india
- insurance term life
- term life policy insurance
- term insurance for home loan protection
- home loan insurance vs term insurance
- is term insurance mandatory for home loan